- Bridging Finance
We'll arrange the best bridging loan available on the market for you. Guaranteed.
- Markets

Bridge Financing Monaco
Bridging finance in Monaco can provide short-term funding for high-value residential and commercial property transactions, including property purchases and equity release from existing assets. Facilities are typically structured around the property, borrower profile and proposed exit strategy.
Monaco’s property market often involves complex cross-border transactions and high-value assets, making the choice of lender and financing structure particularly important. We can help you explore suitable bridging options based on your circumstances, the property and the purpose of the finance.
Get in Touch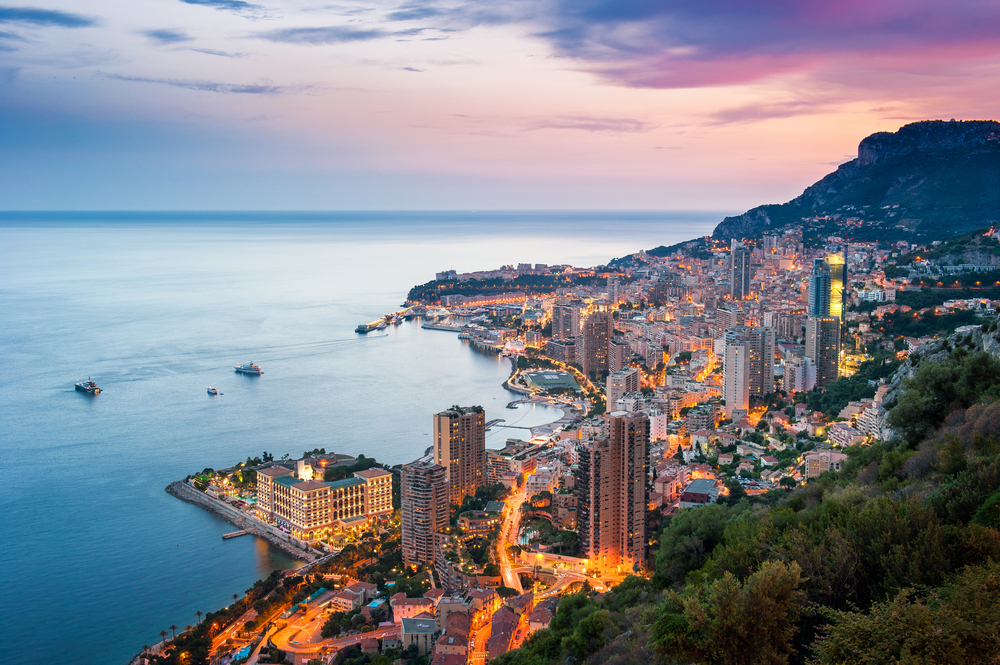
What are Monaco Bridging Loans?
Monaco bridging loans are short-term secured finance designed to provide funding for property purchases, equity release and other time-sensitive transactions where longer-term finance may not be suitable or immediately available.
They can be used for purposes such as:
- Purchasing Monaco property ahead of a planned asset sale
- Releasing equity from an existing Monaco property
- Funding a property purchase while longer-term finance is arranged
- Supporting investment or business-related funding requirements
Finance is secured against suitable property, with the available structure depending on the asset, borrower profile, loan requirements and proposed exit strategy.
What Types Of Property Finance Are Available For High-Value Residential Purchases In Monaco?
Typical Loan-To-Value Ratios For Residential Property Lending In Monaco
What Are The Minimum Lending Amounts For Private Banks And Bridging Finance In Monaco
How Equity Release Works On Monaco Luxury Properties
Which Property Types Are Most Suitable For Financing In Monaco
How International And Middle Eastern Clients Can Access Property Finance In Monaco
Can Existing Assets Under Management Be Transferred To Support Monaco Property Financing
High-value residential purchases in Monaco can be funded through several types of property finance, with the appropriate structure depending on the property, loan size, borrower profile and wider financial position. Options may include dry lending, private bank mortgages, bridging finance and equity release.
Indicative lending parameters can vary significantly between lenders. Dry lending may be available from around €500,000, while private bank finance is typically considered for higher-value properties and may involve an assets-under-management relationship. Bridging finance can be available for larger transactions, subject to the property, ownership structure and proposed exit.
Lenders will assess factors including the property's value, location and marketability, the borrower's liquidity and the overall structure of the transaction before determining the available terms.
Loan-to-value (LTV) levels for residential property finance in Monaco vary according to the lender, property and borrower’s financial profile. For suitable transactions, residential lending may be available at up to around 75% LTV, subject to individual assessment.
Bridging finance is typically structured at more conservative leverage levels, with prime residential property potentially supporting up to around 60% LTV. Private bank lending can follow different criteria, particularly where the borrower has a wider banking relationship or significant assets.
Factors that can influence the available LTV include:
- Property location, value and marketability
- Borrower liquidity and financial strength
- Ownership structure
- Loan size and purpose
- Proposed exit strategy
Final LTV and lending terms are determined by the individual lender and will depend on the circumstances of the transaction.
Monaco property finance is generally geared towards high-value transactions, with minimum loan sizes varying according to the type of lending and the lender’s criteria.
- Dry lending: From around €500,000, typically for properties valued at €650,000 or more
- Private bank mortgages: Often from around €2 million, with some lenders requiring a wider assets-under-management relationship
- Bridging finance: Typically from around €3 million for suitable high-value property transactions
- Development finance: Larger facilities may be available for qualifying projects, subject to project viability and lender requirements
Minimum loan sizes are indicative and can vary between lenders. The property, borrower profile, ownership structure and proposed use of the finance will all be considered when determining whether a transaction meets the relevant criteria.
Equity release can allow property owners to raise capital from an existing Monaco property without selling the asset. For suitable high-value properties, lenders may consider releasing a proportion of the property’s value, subject to the borrower’s financial position and the lender’s criteria.
Funds may be used for purposes such as:
- Renovating or improving an existing Monaco property
- Purchasing another residential property in Monaco
- Supporting wider investment or liquidity requirements, where permitted by the lender
Some Monaco lenders apply specific requirements to how equity release proceeds can be used. The available loan amount and structure will depend on the property value, existing borrowing, borrower profile and lender requirements.
Financing in Monaco is generally focused on high-quality residential property in established locations, where the asset offers strong marketability and a clear route to repayment or refinancing.
Property types that may be considered include:
- Prime residential apartments
- Penthouses and luxury villas
- High-value residential investment properties
- Selected properties undergoing refurbishment or repositioning
Properties with more complex characteristics, such as large estates, rural properties or unusual structures, may require additional assessment. Commercial and mixed-use assets can also be considered in certain circumstances, subject to lender appetite and the specifics of the transaction.
International and Middle Eastern clients can access a range of property finance options in Monaco, with lending structures tailored to the property, borrower profile and overall financial position.
Depending on the circumstances, financing may include private bank mortgages, bridging finance or other bespoke lending arrangements. Some private banks may also consider wider banking relationships and assets held with the institution when assessing a borrowing request.
Eligibility, loan structure and available terms vary between lenders and depend on factors such as liquidity, property value, residency, ownership structure and the proposed use of the finance.
Some private banks may allow existing assets under management (AUM) held with another institution to be transferred as part of a new financing relationship. This can be considered when structuring mortgage or bridging finance for a Monaco property purchase.
Moving assets to the lending bank may form part of the overall assessment, particularly for higher-value transactions. The amount of AUM, the type of assets and the proposed financing structure can all influence the terms available.
Any transfer would be subject to the receiving bank’s requirements, due diligence and approval, with the final financing structure assessed according to the client’s circumstances.
We're Here To Help.
We can help you explore bridging finance and equity release options for property in Monaco. Get in touch to discuss your requirements and we’ll help you understand the available funding structures and next steps.
Let’s Talk
How Fast Can I Access Funds With A Monaco Bridging Loan?
Bridging finance can often be arranged more quickly than traditional property lending, particularly when the transaction is straightforward and the required information is available from the outset.
The timeframe can depend on factors such as:
- Property valuation and legal requirements
- Ownership and borrower structure
- International due diligence
- Complexity of the security
- Clarity of the proposed exit strategy
Prime Monaco property and well-prepared applications may allow lenders to progress matters efficiently, but the final timeframe will depend on lender requirements and the circumstances of the transaction.
Can Monaco Bridging Finance Be Arranged Through A Corporate Entity?
Bridging finance can be structured where the property is owned through a company or other corporate entity, subject to the lender’s requirements and the ownership structure.
This can be relevant for international property owners using corporate structures for investment, succession planning or portfolio management. Lenders will typically review the entity, its ownership, the underlying property and the borrower’s wider financial position as part of their assessment.
Corporate ownership does not automatically prevent access to Monaco bridging finance, although the structure may affect the documentation, due diligence and terms available.
Do Lenders Have Criteria For International Bridging Loans And Equity Release?
Lenders assess international bridging finance and equity release against a range of factors, including the property, borrower profile, ownership structure and proposed exit strategy.
International transactions may involve additional considerations such as residency, the jurisdiction where the property is located, the source of funds and any corporate structures involved. The lender will also need to establish that the proposed borrowing and repayment strategy are appropriate for the transaction.
Criteria vary between lenders, so eligibility and available terms depend on the individual circumstances of the application.
Can I Borrow A Significant Amount Against International Property?
Large international bridging facilities can be available for suitable property transactions, including multi-million-pound loans. The amount a lender may consider depends on factors such as the property value, location, borrower profile, ownership structure and proposed exit strategy.
Higher-value transactions are typically assessed on a bespoke basis, with lenders considering the quality of the security and the overall strength of the application.
Do I Have To Borrow In GBP?
International bridging finance can be available in different currencies, so the loan does not necessarily have to be denominated in GBP. The appropriate currency will depend on the property, where the funds will be used and the lender’s requirements.
For example, a property in Spain could potentially be used as security for a facility in euros, while a borrower may require funding in another currency for a separate investment or project. Currency availability and any associated exchange-rate considerations should be assessed as part of the overall financing structure.
What Are The Typical Loan Terms / Duration For These Loans?
Monaco bridging loans are generally short-term facilities, with the available term depending on the lender, transaction structure and proposed exit strategy. Facilities may be arranged for several months or longer where the circumstances require it.
The appropriate term will take into account the expected timing of the repayment route, whether that involves refinancing, a property sale or another source of capital. Lenders will assess the proposed term alongside the overall strength of the application.
What Is An Exit Strategy, And Why Is It Essential?
An exit strategy sets out how the bridging loan is expected to be repaid at the end of the agreed term. Common routes for Monaco transactions include selling the secured property, refinancing onto longer-term finance, or using capital released from another asset.
Lenders consider the proposed exit when assessing an application, as it needs to provide a realistic route to repayment within the expected timeframe. The strength and viability of the exit can also influence the structure and terms of the facility.
Global Bridging helped connect me with a lender that would let me release significant equity from my international property. Great service!
Borrower International property owner
We arranged an international bridging loan for a HNWI with multiple properties around the world. Global Bridging helped us access a lender that would let our client borrow via one of the corporate structures we administer. The whole process was fast and easy even though we had an unusual and complex situation.
Corporate Trustee International corporate and trust services provider
I faced losing my deposit on a property I was buying abroad because I couldn't get the international mortgage I needed. Global Bridging arranged an international loan for me, which meant I could get the transaction over the finish line without giving up my initial investment.
Borrower European property owner